
Property Damage Insurance Claims, Made Easier
We document and scope your damage, bill your insurance carrier directly, and work hand-in-hand with your adjuster — through mitigation and the rebuild that follows — so your claim moves, you are not fronting the cost of covered repairs, and you can focus on your family.
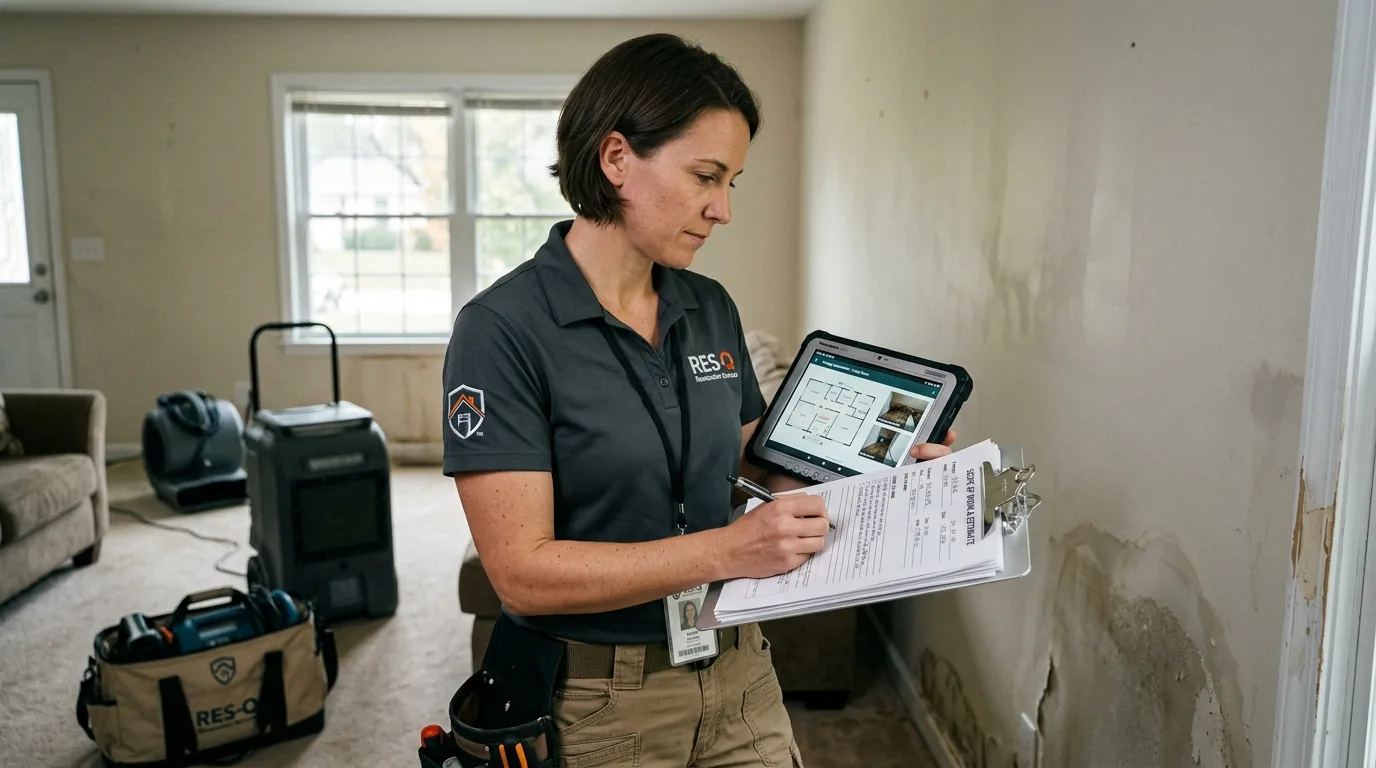
A property damage claim can feel like a second disaster. Skyline has done this many times, and we make the process as painless as possible by giving your insurance company exactly what it needs: clear photos, moisture readings, a detailed scope of repairs, and prompt communication — from the first emergency call through the finished rebuild.
How We Support Your Claim
- Document all damage with photos and moisture readings on arrival
- Provide a detailed, line-item scope of work
- Communicate directly with your adjuster
- Bill your insurance carrier directly, so you're not fronting the cost
- Coordinate mitigation, repairs, and the rebuild so timelines line up
- Keep you informed at every step
What's Usually Covered
Sudden, accidental damage — wind-driven rain, a roof breach, a burst supply line, flash-flood intrusion — is commonly covered by homeowner's policies. Gradual leaks, deferred maintenance, and some flood scenarios may not be. We'll document the cause and let the evidence speak, but coverage is always your carrier's decision.
This page is general information, not legal or insurance advice. Review your policy and speak with your carrier or a licensed professional about your specific situation.
Common Questions
Will my homeowner's insurance cover monsoon damage?
Sudden, accidental storm and water damage is often covered, while long-term seepage or neglect usually isn't. Every policy is different — we document the damage so your claim is presented clearly, but your carrier decides coverage.
Should I file the claim before or after I call you?
Call us first if there's active damage — fast mitigation limits the loss and is something insurers expect. We can document the damage as we stabilize it, which helps your claim.
Do you bill the insurance company directly?
Yes. We bill your insurance carrier directly and work hand-in-hand with your adjuster — providing detailed photos, moisture readings, and line-item scopes — so you're not stuck fronting the cost. You're responsible for your deductible and anything your policy doesn't cover.
What if my claim is underpaid?
If the carrier's first payment misses part of the damage — including the reconstruction scope — we document the full extent and submit detailed supplements to help get the complete repairs covered.
Storm, water or fire damage? Let's get your claim moving.
Free inspection, full documentation, and a team that works with your insurer — through the rebuild.